Introduction
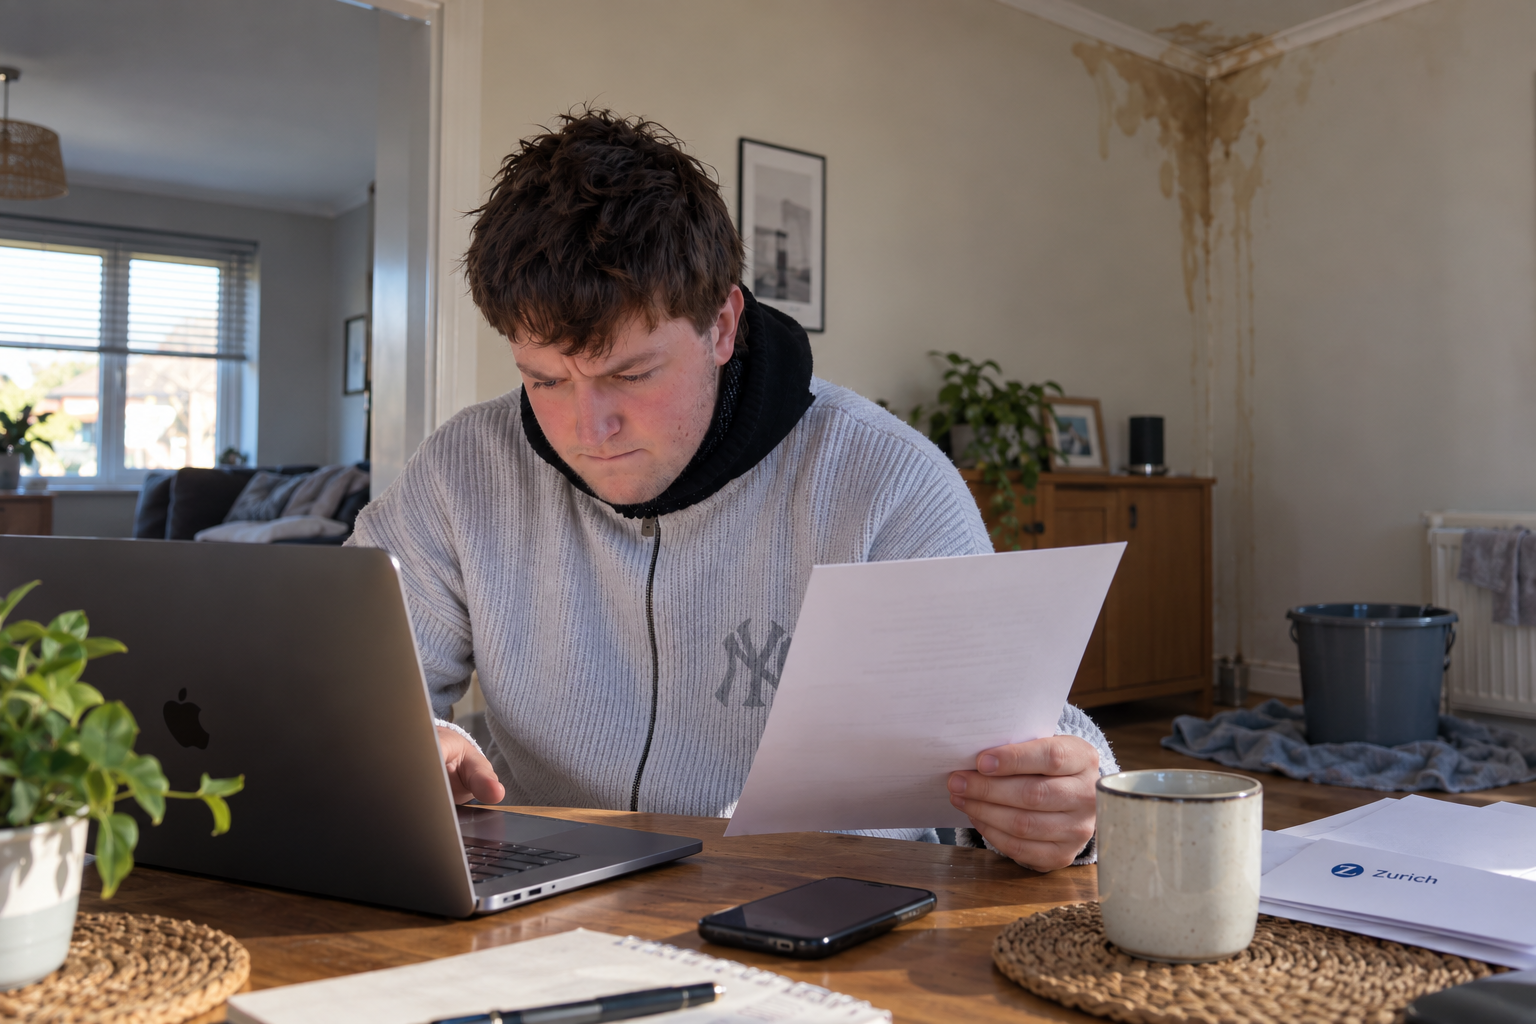
Whether it's a burst pipe damaging your kitchen, a storm affecting your roof or a break-
in at home, discovering damage to your property can be stressful. If you've never made a
home insurance claim before, knowing who to contact, what information you'll need
and how your claim is assessed can help you understand what to expect.
Here are five key things to know about making a home insurance claim.
1. How do you start a home insurance claim?
The first step is to contact your insurer or insurance broker as soon as possible after
discovering the damage. Your policy documents should explain how to report a claim
and any notification deadlines that apply.
You'll generally be asked what happened, when it occurred and what was damaged or
lost. If you've missed a reporting deadline, you should still contact your insurer rather
than assume your claim will automatically be refused. The effect of late notification will
depend on the policy and circumstances.
It's also important to take reasonable steps to prevent further damage, provided it's
safe. This might mean turning off the water supply following a burst pipe or arranging
temporary protection for a damaged roof.
Keep receipts for emergency work and, where possible, contact your insurer before
arranging permanent repairs.
2. What happens after you report the damage?
Your insurer will review the information provided and consider whether the damage is
covered. Straightforward claims may be handled directly, while more complex losses
may involve a loss adjuster.
A loss adjuster is appointed by the insurer to investigate the circumstances, assess the
damage and help establish the claim's value.
A loss assessor, by contrast, is someone you can appoint to represent your interests,
generally at your own expense.
Under the Central Bank of Ireland's Consumer Protection Code, insurers must, where
relevant, inform claimants in writing within five working days of receiving notice of a
claim about their option to appoint a loss assessor at their own expense.
3. What evidence might you need?
Your insurer may request supporting information to establish what happened and the
extent of your loss. The evidence required will depend on the claim.This could include photographs of damaged areas, receipts or valuations for
belongings, repair quotations and proof of ownership for stolen items.
For example, if a leak damages flooring or furniture, taking photographs before cleaning
up or carrying out repairs can provide useful evidence.
If your claim involves theft or criminal damage, you may also need to report the incident
to An Garda Síochána.
Keeping copies of documents and responding to information requests can help avoid
unnecessary delays.
4. How much will you have to pay yourself?
Even where damage is covered, your insurer may not pay the full cost. The amount
received can be affected by your policy's excess, cover limits and other terms.
An excess is the amount you contribute towards an insured claim. For example, if an
accepted claim is valued at €2,000 and the excess is €300, the insurer would generally
pay €1,700, assuming no other deductions or limits apply.
Underinsurance can also affect a payout. This occurs when your home or belongings
are insured for less than their appropriate rebuild or replacement value. Depending on
the policy, underinsurance may reduce payment even for partial damage.
Reviewing your sums insured regularly can help reduce this risk.
5. How is your claim settled?
If your claim is accepted, settlement may involve repairs, replacement of damaged
belongings or a cash payment.
Where an insurer arranges repairs through a third party as part of a direct settlement,
Central Bank rules require certification that the work restores the property to at least its
pre-damage standard.
Insurers must communicate a claim decision within five working days of making it.
Claimants must generally have at least ten working days to consider a settlement offer,
unless they waive that period. Once a monetary settlement is accepted, payment must
generally be made within ten working days. These deadlines relate to individual stages,
not the entire process.
If your claim is declined, the insurer must explain why and outline any available appeals
mechanism.
If you're unhappy with the outcome or handling of your claim, you can complain to your
insurer. It must make reasonable efforts to resolve complaints within 40 working days. Ifthe matter remains unresolved, or you're dissatisfied with its final response, you may be
able to refer it to the Financial Services and Pensions Ombudsman (FSPO).
Conclusion
Every claim is different, but understanding your policy and the steps involved can help
you make informed decisions if your home or belongings are damaged
Need More Assistance?
If you have further questions, you can contact Insurance Ireland's Information Services team:
Email:feedback@insuranceireland.eu
Tel: (01) 676 1820